Can You Hold Bitcoin ETFs in a TFSA? Rules for 2026
Spot bitcoin ETFs listed in Canada qualify for a TFSA, while bitcoin itself does not. Compare MERs from 0.32% to 1.47% and the CRA rules that apply.
Interac vs wire transfer for crypto in Canada: e-Transfers are free but capped at $3,000 a day at big banks, a $25,000 wire costs $45 to $85 in bank fees.

By Mikko Mikailov6 min read
Interac e-Transfer and bank wire solve different problems when you fund a crypto account in Canada. An e-Transfer costs nothing at Kraken, Bitbuy, Newton and Shakepay and credits within minutes to a day, but TD, CIBC and Tangerine cap personal sending at $3,000 per day and $10,000 per week. A wire carries a bank fee of $45 to $57 at the Big Five for a $25,000 transfer, takes 1 to 5 business days to credit, and starts at $10,000 on three of those four platforms. Below $10,000 the choice is made for you. Above it, the question is whether a single entry date is worth a fee of 0.2% on $25,000.
Interac e-Transfer runs on a retail network built for payments between people. Each bank sets its own sending caps under a network ceiling of $25,000 per transfer, and the five largest banks set personal limits far lower. The transfer is final once the recipient deposits it.
A wire goes through Lynx, the high-value payment system Payments Canada has operated since 30 August 2021. Lynx settles each payment in central bank money the moment it clears, and Payments Canada describes the result as final and irrevocable once the receiving institution has it. The system runs on business days only, so a wire sent on a Friday afternoon before a long weekend sits until Tuesday. Each bank also sets its own internal cut-off time.
The settlement is instant. The credit is not. A crypto platform receives the wire into a pooled account and has to match it to you, and Newton and Shakepay do this by a reference code you add to the wire instructions. That matching is the 1 to 5 business days the platforms quote, and it is also where wires get lost.
There is a second difference, less visible. The big banks do not let you send a wire to another institution from online banking. RBC, TD, Scotiabank and CIBC process them at a branch, according to fee tables compiled from their published guides. Tangerine and EQ Bank do not offer outgoing wires at all. A wire, for a client of those banks, starts with moving the money to another bank first.
The four platforms below accept both rails. Their published terms as of 5 November 2026 are:
| Platform | e-Transfer deposit cap | Wire minimum | Platform wire fee | Wire credit time | Reference code |
|---|---|---|---|---|---|
| Kraken | $10,000 per day, $30,000 per week | $100 | Free | 1 to 5 business days | Not stated |
| Bitbuy | $15,000 per deposit | $10,000 | Free | 0 to 2 business days | Receipt upload in app |
| Newton | $10,000 per transfer, $70,000 per week | $10,000 | Free from $10,000 | Not stated | Required |
| Shakepay | $10,000 per transfer | $10,000 | Free | Up to 2 to 3 business days | Required |
Newton's own pages disagree on its floor. Its wire instructions refuse wires under $10,000, while its limits page lists a $5,000 minimum and a $1,000,000 maximum per wire. The instructions are what the receiving team applies. Kraken routes Canadian dollar wires through Credit Union Atlantic and states that its deposit fees exclude whatever your bank charges to send.
The broader set of funding routes, including card and bill payment, is covered in our guide to buying and selling crypto with CAD.
The platforms charge nothing on either rail, so the cost sits with your bank. For a single $25,000 wire to another institution, the published outgoing fees work out as follows:
| Bank | Outgoing wire fee rule | Fee on $25,000 |
|---|---|---|
| RBC | From $45 | $45 |
| TD | $50 to another bank | $50 |
| BMO | $40 plus a $10 communication charge | $50 |
| CIBC | $50 from $10,000.01 to $50,000 | $50 |
| Scotiabank | 0.2%, minimum $30, maximum $100, plus $7 domestic | $57 |
| National Bank | 0.34%, minimum $20, maximum $70, plus $15 | $85 |
| Simplii Financial | $50 from $10,000.01 to $50,000 | $50 |
On $25,000, a $50 wire costs 0.20%. On $100,000 the same flat fee falls to 0.05%, while Scotiabank's percentage stops at its $100 cap plus $7.
The e-Transfer route costs nothing in fees and a great deal in time. At TD's limits of $3,000 per day and $10,000 per 7 days, $25,000 enters the account in three tranches over three weeks: $10,000, then $10,000, then $5,000. Each tranche buys at a different price. Over three weeks, bitcoin's price could move in either direction by far more than the 0.2% a wire costs. Whether that spread of entry prices is a cost or a feature depends on the buyer, and the buyer alone.
The threshold follows. Under $10,000, the e-Transfer is the only route to Bitbuy, Newton and Shakepay. Between $10,000 and the weekly e-Transfer limit, both work, and the e-Transfer still wins on cost. Above the weekly limit, the wire buys a single entry date for a flat fee between $45 and $107 at the banks listed.
A wire has more ways to fail than an e-Transfer, and the platforms' help pages trace those failures to the instructions. The sequence is short:
The reference code ties the wire to your account inside the platform's pooled bank account. Newton and Shakepay require it, and Newton warns that a wire without it faces a long delay. Name matching is strict. Newton refuses wires from a business account to a personal account, and Shakepay asks for a consent letter from both holders of a joint account.
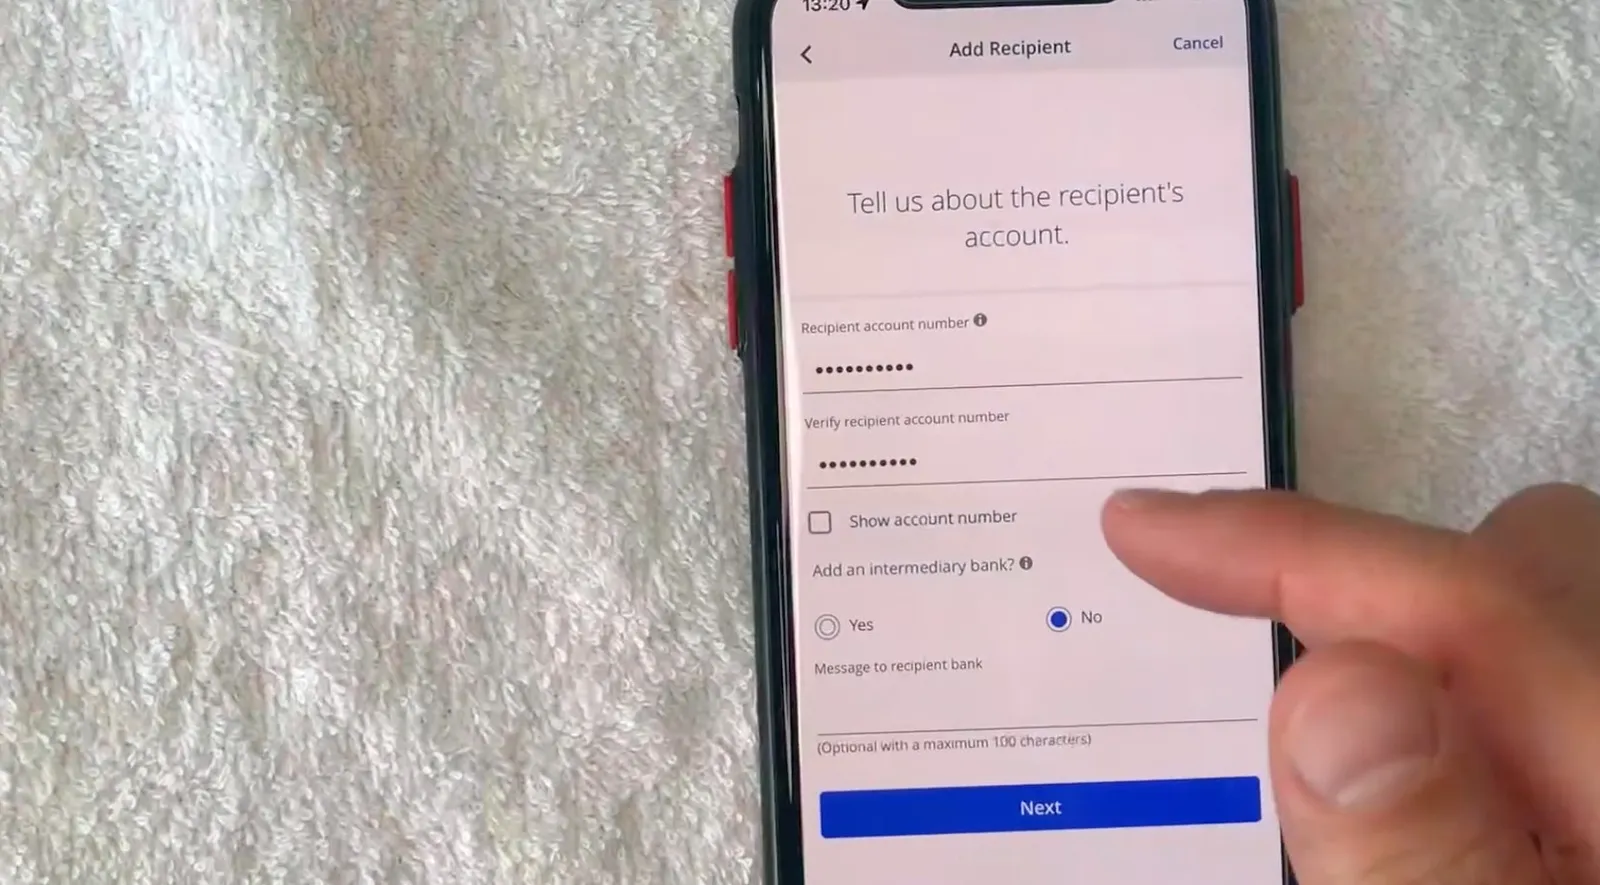
Domestic CAD wires need the beneficiary name, institution number, transit number and account number, with no SWIFT code. After the wire leaves, Bitbuy asks for the amount and processing date from the bank receipt, and Shakepay asks for the wire document itself. A wire sent after the bank's cut-off time, or on a statutory holiday, settles on the next business day.
Neither rail has a reversal button, so the errors on this route cost real money. They fall into three groups.
A missing reference code, a wire below the platform minimum or a name that does not match the platform profile all end the same way. The platform sends the money back, and the fees come out of it. Newton charges $51.50 CAD to return a wire sent incorrectly. The sending bank adds its own charge on top, and CIBC lists $35 per payment for a returned or amended wire.
Lynx settles a wire as final and irrevocable. A bank cannot pull it back once the receiving institution has it, whatever the reason for the request. An e-Transfer is equally final once deposited, but its smaller size limits the damage of a mistake.
Legitimate platforms show their banking details inside the logged-in account. Wire instructions that arrive by email or chat, or a message announcing a changed account number, are a fraud signal. A wire to a platform that is absent from the CSA list of authorized trading platforms could be lost with no Canadian regulator in a position to help.
The exit carries costs too, since the receiving bank charges for an incoming wire. Our guide to withdrawing crypto to a Canadian bank sets out those fees by platform.
Mikko has been writing about money since 2015, covering payment services, trading platforms and crypto for readers in several markets. He leads exchange and wallet reviews at CryptoInfoBase.
Spot bitcoin ETFs listed in Canada qualify for a TFSA, while bitcoin itself does not. Compare MERs from 0.32% to 1.47% and the CRA rules that apply.
Buying bitcoin with Interac e-Transfer in Canada: deposit rules, platform limits, bank caps of $3,000 a day, real fees on a $1,000 order and the scams to avoid.
Crypto tax records in Canada: what the CRA asks you to keep, why the six-year clock starts at the sale, how to export exchange data and build an ACB ledger.